
Introduction
Overview of Inheritance Tax
In Australia, inheritance tax—often referred to historically as death duties—is no longer applied at a federal or state level. However, this does not mean that beneficiaries and estate givers avoid tax obligations entirely. Instead, tax implications arise through capital gains tax (CGT), superannuation death benefits, rental income, income tax, and the administration of the deceased estate. Understanding these rules is essential, particularly when dealing with assets like Australian residential property, bank accounts, family trusts, and foreign assets.
Tax obligations can vary depending on whether assets are transferred as a lump sum, income stream, or through testamentary trusts. Factors such as tax residency, the main residence exemption, cost base rules, CGT discount eligibility, valuation certificates, and market conditions all influence the tax outcome. When international inheritances involve countries like the United Kingdom, South Korea, or the United States, double taxation agreements and foreign tax residency rules must also be considered.
Purpose of the Blog
As an Australian financial planner, my goal is to simplify how inheritance tax considerations actually work under Australian tax law—including CGT, estate administration, and superannuation death benefits. Whether you are preparing your own estate planning strategy or anticipating an inheritance, understanding these concepts can help protect your wealth and minimise tax. This guide will also illustrate how a Will and Estate Lawyer, a legal personal representative, and financial professionals such as Equip Super, Togethr Trustees Pty Ltd, or an accountant play a role in the administration of the estate.
Understanding Estate Taxes in an Australian Context
No Formal Inheritance Tax — But There Are Taxes
Australia abolished inheritance tax decades ago, but several taxes still apply indirectly:
- Capital Gains Tax (CGT) when beneficiaries later sell inherited assets.
- Income tax on rental income from inherited properties.
- Medicare levy applied to assessable income.
- Tax obligations on certain superannuation death benefits.
These taxes operate differently from estate taxes in the United States or United Kingdom. While those jurisdictions levy direct estate tax or inheritance tax, Australian jurisdictions focus on CGT rules, superannuation law, and ongoing tax obligations related to inherited assets.
Superannuation Death Benefits
A superannuation death benefit may be paid as a lump sum or income stream from a super fund. Taxation depends on:
- Whether the beneficiary is a tax dependant (spouse, minor child, interdependent relationship, etc.).
- The components of the superannuation account (taxable/tax-free).
- Whether the super fund’s Product Disclosure Statement (PDS) or Target Market Determination (TMD) outlines particular restrictions.
Non-tax dependants may pay tax on the taxable component. Professional advice is especially important when restructuring superannuation benefits or using asset management strategy tools like amplify 11.
Capital Gains Tax and Inherited Assets
Understanding Cost Base and CGT Rules
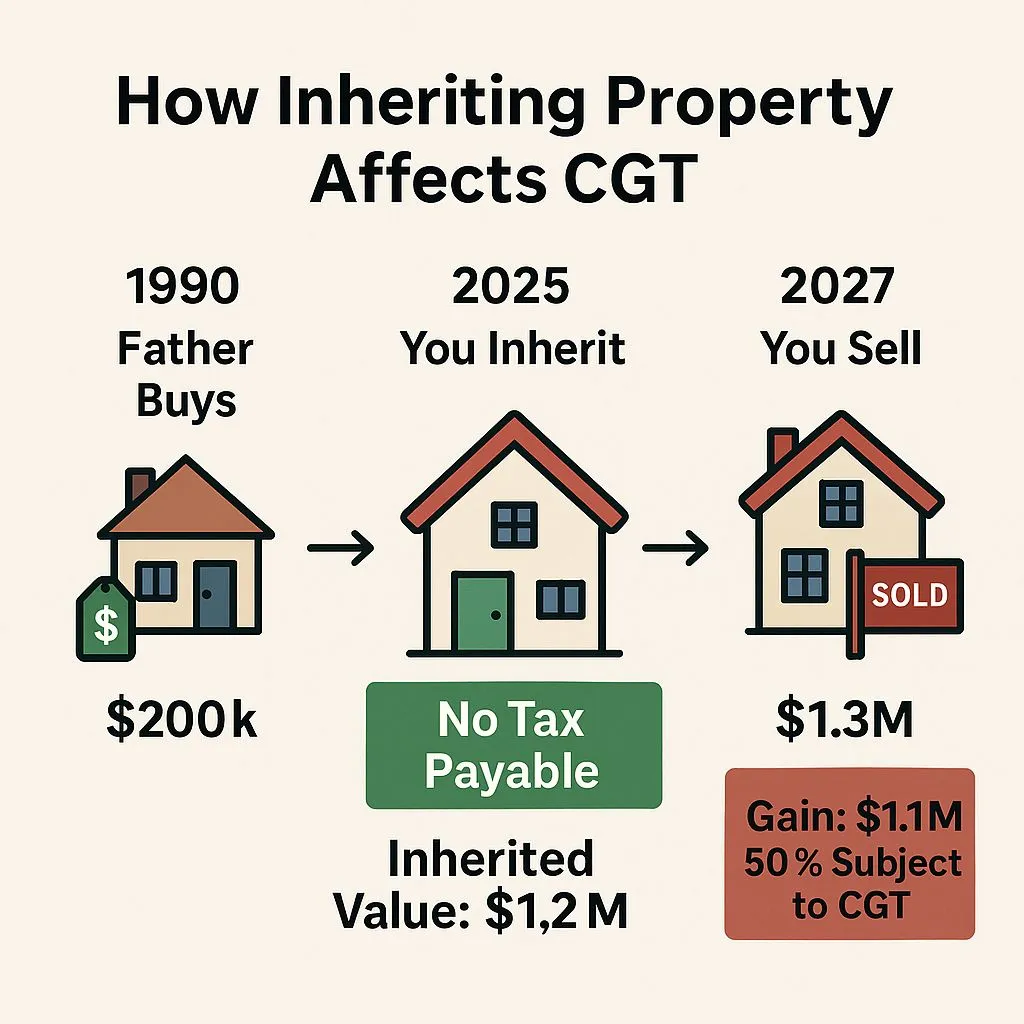
When inheriting assets such as real estate, shares, or foreign assets, CGT applies only when the beneficiary eventually sells the property. The cost base is generally:
- The market value at the date of death, or
- The original cost base if the deceased purchased before CGT started (20 September 1985).
A valuation certificate or certified appraisal is often necessary to establish the correct cost base.
Main Residence & Two-Year Rule
Under Australian Tax Office guidelines:
- If the deceased’s main residence (Principal Place of Residence) is sold within two years, the full CGT main residence exemption may apply.
- If held longer, CGT may be apportioned based on non-main-residence days.
- Extensions can be approved by the Australian Taxation Office depending on estate administration delays or life events.
CGT Discount
If beneficiaries hold the asset for more than 12 months before selling, the CGT discount (typically 50%) may apply—subject to tax residency status.
Estate Administration & Tax Obligations
Role of the Legal Personal Representative (LPR)
The executor or administrator—known legally as the legal personal representative—is responsible for:
- Managing and protecting estate assets.
- Lodging the deceased’s final tax return.
- Reporting rental income, trust income, or business income.
- Determining tax residency for foreign resident beneficiaries.
- Managing international tax interactions under Double Taxation Agreements.
Tax Returns Required
The ATO may require:
- Final tax return (date of death return).
- Trust tax return for the deceased estate (administration of the estate period).
- Individual tax returns for beneficiaries receiving assessable income.
These obligations vary depending on whether the estate earns income (e.g., rental income from real estate) before distribution.
International Inheritances & Foreign Residency
With increasing overseas migration, it’s common for Australians to inherit from the United Kingdom, South Korea, or the United States. International inheritances may trigger:
- Foreign estate taxes.
- CGT on foreign assets when later disposed of in Australia.
- Tax residency complications.
- Double Taxation Agreement considerations.
Australian foreign resident rules also affect beneficiaries who are no longer Australian tax residents, especially when they sell property or distribute income from family trusts.
Planning Strategies for Minimising Tax
Estate Planning Techniques
Effective estate planning can reduce future tax burdens and protect wealth. Strategies include:
- Establishing testamentary trusts to distribute income tax-effectively.
- Using trustee discretion to allocate income across lower tax brackets.
- Ensuring a valid Will and binding death benefit nominations.
- Reviewing superannuation funds such as Equip Super or Togethr Trustees Pty Ltd for optimal outcomes.
Restructuring Superannuation Benefits
You may restructure superannuation benefits to maximise tax-free components or ensure assets pass efficiently to dependants.
Real Estate Planning
When beneficiaries inherit real estate, planning might involve:
- Deciding whether to sell property or retain it for rental income.
- Considering market conditions and the property’s cost base.
- Evaluating the two-year CGT rule.
- Reviewing Queensland Government or other state-based rules if the asset is location-specific.
Conclusion
Why Understanding Inheritance Tax Matters in Australia
While Australia does not impose direct inheritance tax, estate taxes and tax implications arise through CGT, income tax, superannuation law, and ongoing tax obligations. Being proactive can significantly reduce the financial burden on your loved ones.
Working with a financial planner, accountant, or Will and Estate Lawyer ensures compliance with Australian tax law and effective management of your financial legacy.
Disclaimer: The information provided on this blog is general in nature and does not constitute specific financial advice. It is intended for educational purposes only and should not be relied upon as a substitute for professional financial advice tailored to your individual circumstances. For personalized financial assistance, please contact Brandon Foster via the contact page.